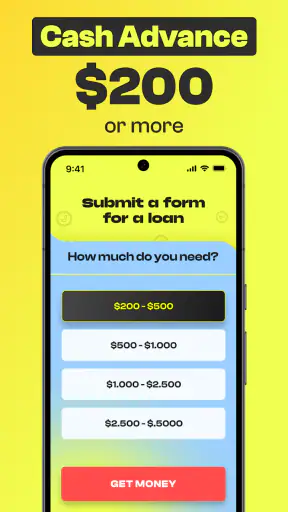
When an unexpected bill lands before payday, the appeal of Cash Advance - No credit Check is easy to understand. It is a free finance app from D.J. Advance App that presents itself as a way to look for an instant cash advance without relying on a traditional credit check. I approached it less like a promise of effortless money and more like a tool to examine carefully when time is tight. That distinction matters: an app can make the search for short-term help more convenient, but it does not automatically make borrowing affordable or suitable.
My overall impression is that this app is most useful for someone who wants a simple starting point while comparing short-term cash options. It is not the right choice for treating every payday gap as normal, and I would not use any cash-advance service without checking the complete repayment terms first. The app’s strong public reception—an average rating of 4.7 from around 35 thousand ratings—suggests that many people find the experience worthwhile, but a rating cannot replace reading the details of an offer.
How I Would Decide Whether It Fits
Start with the real problem, not the promise of speed
Before opening the app, I would write down the exact amount needed, the date the money must be available, and the date I could realistically repay it. That small exercise keeps an urgent expense from turning into an open-ended borrowing decision. A shortfall for a necessary prescription is different from a shopping purchase, and a bill due tomorrow is different from a bill that can be moved without a penalty.
Cash Advance - No credit Check is aimed at the first stage of that process: finding possible access to cash when a conventional loan application may be inconvenient or unavailable. The phrase “no credit check” should not be interpreted as “no eligibility rules” or “no cost.” I would still expect an application or offer to involve its own requirements, repayment conditions, and possible charges. The practical question is not simply whether money can be requested, but whether the total repayment fits comfortably into the next budget.
Compare the full cost, not just the amount received
My most important tip is to compare the amount you receive with the total amount you must give back. Look for any service charge, expedited-transfer charge, membership condition, recurring payment, or other fee presented during the process. Also check whether repayment is taken automatically and what happens if the account balance is too low. A small-looking charge can become expensive when it is attached to a very short repayment period.
This is where a cash-advance app differs from a budgeting app. A budgeting tool helps you plan money you already have; this type of service helps you explore access to money you do not currently have. The convenience can be valuable, but the financial risk is higher. I would treat the app as a comparison and decision tool rather than as a replacement for an emergency fund.
Keep the phone and account setup practical
The app runs on Android devices using version 7.0 or later, which makes it accessible to many older phones as well as newer models. It is listed for Everyone, and the current version is 1.1.3. Those details make the basic download decision straightforward, but they do not answer the more important question of whether a particular offer is safe for your circumstances.
I would use a private connection, keep the operating system updated, and read every screen before submitting personal or financial information. I would also avoid rushing through an approval flow simply because the wording emphasizes urgency. If an offer is unclear about repayment, I would stop and look for another option rather than assuming the missing detail will become obvious later.
A realistic payday-gap example
Imagine that a utility bill is due on Friday, while your regular paycheck arrives the following week. I would first contact the utility provider to ask whether the due date can be moved or whether a payment arrangement is available. If that fails, I would compare the app’s available option with an overdraft, a credit-union product, help from a trusted family member, or a credit card payment—without assuming any of those alternatives is automatically cheaper.
If I still considered a cash advance, I would enter the process knowing the exact amount needed rather than requesting the maximum available. I would then calculate what remains after repayment: rent, food, transport, and other fixed commitments must still be covered. If repaying the advance would create another shortage next week, the app has not solved the problem; it has moved it forward.
Three details I would check before accepting anything
I would identify the repayment date and confirm that it matches my actual income schedule, not an optimistic estimate.
I would record the total repayment amount in a note or screenshot so I could compare it with other choices without relying on memory.
I would check whether accepting the service changes my regular bank balance in a way that could trigger other payments or fees.
These steps sound basic, but they are especially important with fast financial products. Speed reduces the time available for reflection, so creating a short checklist restores some control.
Where the app wins for the right user
The clearest advantage is convenience. Cash Advance - No credit Check is free to install, and its purpose is immediately understandable. Someone who has already ruled out a payment extension and needs to investigate short-term options can begin in one place instead of searching randomly across the finance category.
I also like the app’s potential value as a first filter for people who may not qualify for conventional credit. A traditional lender may involve a formal credit review, a longer application, or requirements that do not suit a very small, urgent need. This app’s positioning speaks directly to users who want to explore a different route. That does not guarantee approval or affordability, but it explains why the product has attracted more than 500 thousand installs.
Another strength is that the app can encourage a more deliberate comparison if the user treats it as one option among several. I would not open it with the mindset that it must provide the answer. I would use it to understand what is available, then compare the complete terms against alternatives. That approach turns convenience into a benefit without confusing convenience with value.
What may slow me down or make me cautious
The main friction is not necessarily the download or the interface; it is the financial decision that follows. A short-term advance can feel harmless because the amount is smaller than a conventional loan, yet the repayment may arrive at the worst possible moment. If the app shows an offer that depends on a fee, a fast repayment, or an automatic withdrawal, I would consider that structure carefully before accepting it.
I would also be cautious about the gap between the store summary and the details that matter to a borrower. The summary describes access to a cash advance without a credit check, but a responsible decision requires more information than that headline. I would want to understand the provider involved, the total cost, the repayment method, and the consequences of late or unsuccessful repayment before proceeding. The app may help me reach that information, but I would not treat the short description as a complete explanation.
Finally, a finance app is not a substitute for debt support. If I was already using advances repeatedly, borrowing from one payday to cover another, or missing essential payments, I would skip the app and seek help from a nonprofit debt adviser, a credit counselor, or a local financial service. In that situation, another advance can hide the underlying cash-flow problem.
How It Compares With the Usual Alternatives
Traditional personal loans
A bank or credit-union personal loan may be a better fit when the need is larger, the repayment can be spread over a longer period, and the borrower has time to compare formal offers. The application may feel slower and may involve a credit assessment, but the structure can be easier to understand than a very short repayment cycle. I would compare the annual cost, fees, and total repayment rather than choosing solely on speed.
Cash Advance - No credit Check makes more sense as an option to investigate when the need is immediate and conventional borrowing is not practical. It is less attractive when the expense is predictable or recurring. For a regular monthly shortfall, a longer-term budget change is usually more useful than repeatedly using a rapid cash product.
Credit cards and overdrafts
A credit card or arranged overdraft may already be available, which removes some application friction. However, these options can also carry interest, account fees, or penalties, and an unarranged overdraft can be particularly costly. I would compare the exact cost of using the existing facility with the exact repayment cost shown through the app.
The advantage of an existing account product is familiarity: I may already know how repayment works and where to find the terms. The advantage of the app is that it gives me another route when those facilities are unavailable or unsuitable. Neither option deserves automatic preference. The right choice depends on the full cost and whether repayment will be manageable.
Employer advances and community support
Some employers offer early access to earned wages, while community organizations may provide emergency assistance for food, housing, utilities, or medical needs. These options can be worth checking before borrowing, especially when the expense is essential. They may involve different eligibility rules and may not be available to everyone, but they can reduce the chance of adding a new repayment obligation.
Asking a family member or friend can also be emotionally difficult, so I would not describe it as a universally easy alternative. Still, a clear written agreement can sometimes be less expensive than a commercial advance. The important point is to compare the financial and personal consequences honestly rather than assuming an app is more comfortable simply because it is private.
What switching away would involve
Moving from this app to another option is not technically complicated, but the financial cost of switching can be significant if an offer has already been accepted. Before changing direction, I would confirm whether any application has created a repayment obligation, whether money has already been deposited, and whether an automatic withdrawal is scheduled. I would keep records of confirmations and terms so that a second application does not create confusion.
If I had only browsed possible options, switching is easy: I could close the process and compare a credit union, an employer program, or a payment arrangement. If I had accepted an advance, switching would mean managing that repayment first. I would never take a second advance simply to make the first one look affordable. That is the point at which convenience can become a cycle.
Who should use it and who should skip it
I would recommend considering Cash Advance - No credit Check to an adult who has a specific, urgent expense, understands the repayment date, and has already compared less expensive ways to handle the bill. It may also suit someone who wants to explore a cash-advance route without beginning with a conventional credit application.
I would advise skipping it if the money is for a nonessential purchase, if the next paycheck is already committed, or if another loan or advance is still outstanding. I would also avoid it when the terms cannot be understood clearly. A product that requires guesswork is not a good match for a high-pressure financial decision.
My recommendation after weighing the trade-offs
My recommendation is cautious but positive: Cash Advance - No credit Check is worth investigating as a free starting point for a genuine, short-lived emergency, not as a routine payday supplement. The app’s broad availability, simple purpose, and strong user rating make it easy to consider, while its financial category demands more care than an ordinary utility app.
I would install it only after deciding the precise amount needed and identifying at least one alternative. I would compare the total repayment, verify the timing, and leave the process if any important condition was unclear. The best outcome is not simply receiving cash quickly; it is resolving the immediate problem without creating a larger one at the next payday.
In short, use the app as a careful comparison step, never as an automatic answer to a money shortage. For a one-off gap that can be repaid comfortably, it may be a practical option to examine. For recurring financial pressure, a budget review, payment arrangement, credit counselor, or more structured borrowing product is likely to serve you better.
Cash Advance - No credit Check is free, carries an Everyone age rating, and comes from D.J. Advance App. Those facts make it approachable, but my final judgment rests on how responsibly it is used. If you can explain exactly why you need the money, exactly when you will repay it, and exactly what it will cost, the app may deserve a place in your comparison process. If you cannot answer those questions, I would leave it alone.


